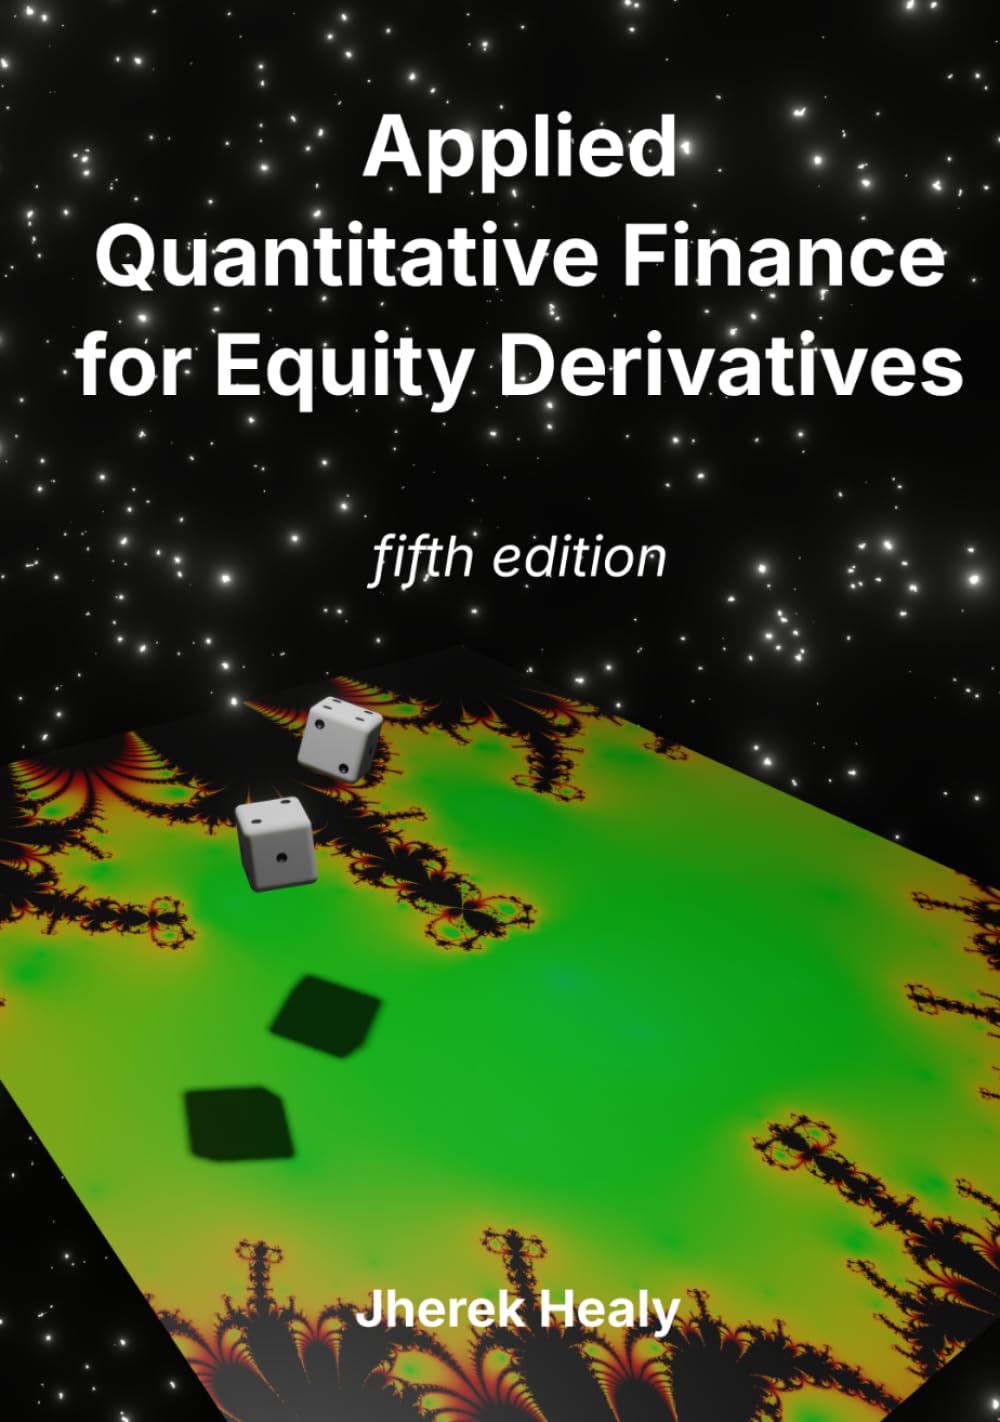
Applied Quantitative Finance for Equity Derivatives: Fifth Edition pdf de graça baixar
de Jherek Healy
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| Baixar grátis | |
| mp3 | Baixar grátis |
| audiobook | Baixar grátis |
| kindle | Baixar grátis |
Descrição do livro
In its fifth edition, this book presents the most significant equity derivatives models used these days. It is not a book around esoteric or cutting-edge models, but rather a book on relatively simple and standard models, viewed from the angle of a practitioner.
A few key subjects explained in this book are:
The January 2025 fifth edition all in color brings the following minor updates:
Autores populares
Icon Group International (289) Publishing lmgdaw (229) Nikolay Krechet (123) Kennie B Journals (118) Charles Nehme (107) webmarbook design (97) Riddler Books (94) Ondrej Sarek (87) Jillo Trukudo (77) dkdesigns Publishing (76) Mint and Cherry Notebooks (74) Maria Emmrich (73) Just Visualize It (72) Various (69) Moonpeak Library (67) Reynhard Boegl (67) Bettina Schipp (66) matlasor Sticker's (66) Talor Press (66) Joseph Alexander (65)