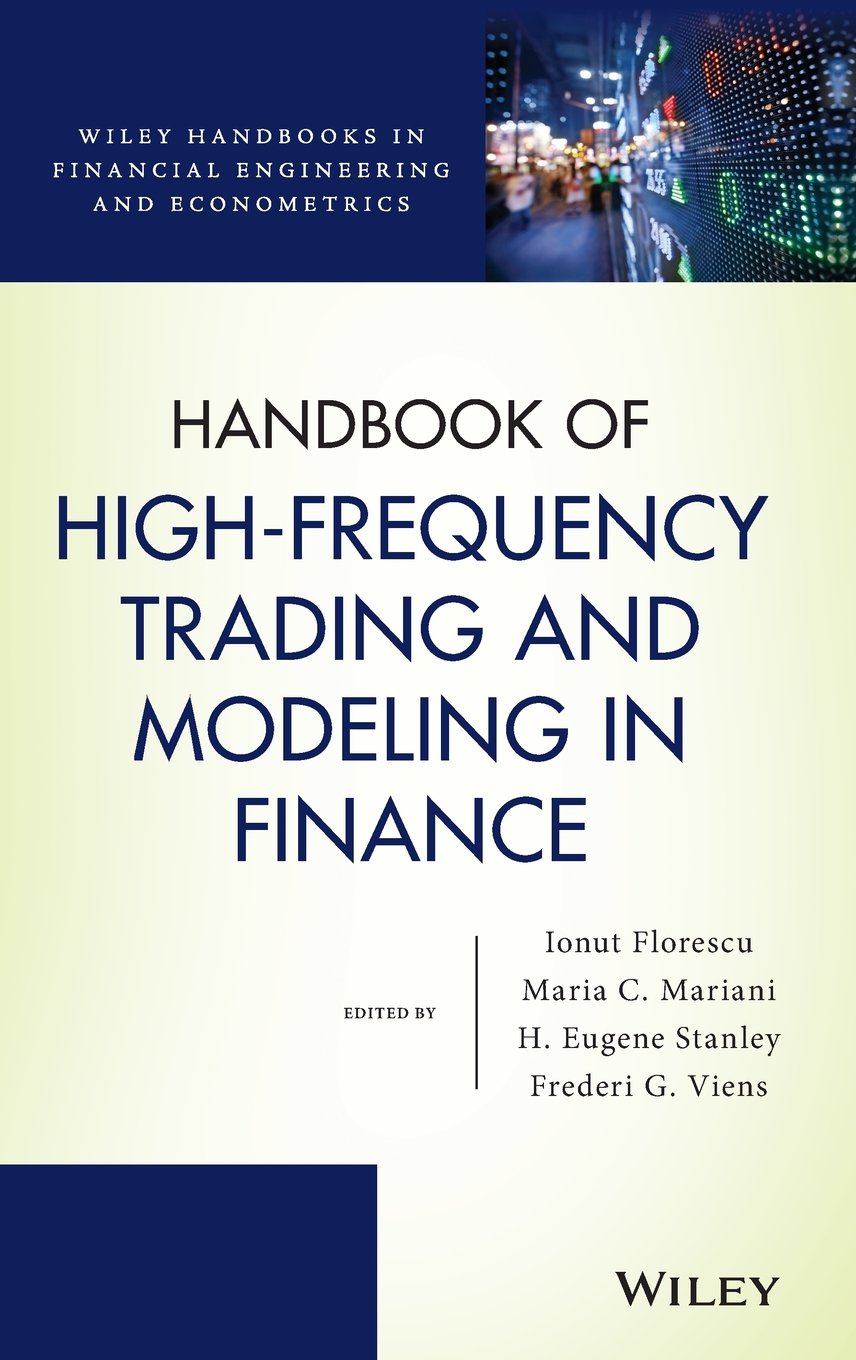
Handbook of High-Frequency Trading and Modeling in Finance: 9 baixar o livro de graça
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| Baixar grátis | |
| mp3 | Baixar grátis |
| audiobook | Baixar grátis |
| kindle | Baixar grátis |
Handbook of High-Frequency Trading and Modeling in Finance: 9
Reflecting the fast pace and ever-evolving nature of the financial industry, the Handbook of High-Frequency Trading and Modeling in Finance details how high-frequency analysis presents new systematic approaches to implementing quantitative activities with high-frequency financial data. Introducing new and established mathematical foundations necessary to analyze realistic market models and scenarios, the handbook begins with a presentation of the dynamics and complexity of futures and derivatives markets as well as a portfolio optimization problem using quantum computers. Subsequently, the handbook addresses estimating complex model parameters using high-frequency data. Finally, the handbook focuses on the links between models used in financial markets and models used in other research areas such as geophysics, fossil records, and earthquake studies. The Handbook of High-Frequency Trading and Modeling in Finance also features: - Contributions by well-known experts within the academic, industrial, and regulatory fields - A well-structured outline on the various data analysis methodologies used to identify new trading opportunities - Newly emerging quantitative tools that address growing concerns relating to high-frequency data such as stochastic volatility and volatility tracking; stochastic jump processes for limit-order books and broader market indicators; and options markets - Practical applications using real-world data to help readers better understand the presented material The Handbook of High-Frequency Trading and Modeling in Finance is an excellent reference for professionals in the fields of business, applied statistics, econometrics, and financial engineering. The handbook is also a good supplement for graduate and MBA-level courses on quantitative finance, volatility, and financial econometrics. Ionut Florescu, PhD, is Research Associate Professor in Financial Engineering and Director of the Hanlon Financial Systems Laboratory at Stevens Institute of Technology. His research interests include stochastic volatility, stochastic partial differential equations, Monte Carlo Methods, and numerical methods for stochastic processes. Dr. Florescu is the author of Probability and Stochastic Processes, the coauthor of Handbook of Probability, and the coeditor of Handbook of Modeling High-Frequency Data in Finance, all published by Wiley. Maria C. Mariani, PhD, is Shigeko K. Chan Distinguished Professor in Mathematical Sciences and Chair of the Department of Mathematical Sciences at The University of Texas at El Paso. Her research interests include mathematical finance, applied mathematics, geophysics, nonlinear and stochastic partial differential equations and numerical methods. Dr. Mariani is the coeditor of Handbook of Modeling High-Frequency Data in Finance, also published by Wiley. H. Eugene Stanley, PhD, is William Fairfield Warren Distinguished Professor at Boston University. Stanley is one of the key founders of the new interdisciplinary field of econophysics, and has an ISI Hirsch index H=128 based on more than 1200 papers. In 2004 he was elected to the National Academy of Sciences. Frederi G. Viens, PhD, is Professor of Statistics and Mathematics and Director of the Computational Finance Program at Purdue University. He holds more than two dozen local, regional, and national awards and he travels extensively on a world-wide basis to deliver lectures on his research interests, which range from quantitative finance to climate science and agricultural economics. A Fellow of the Institute of Mathematics Statistics, Dr. Viens is the coeditor of Handbook of Modeling High-Frequency Data in Finance, also published by Wiley.
Procurando Handbook of High-Frequency Trading and Modeling in Finance: 9? Aqui você encontra tudo sobre este livro de o autor, publicado por Wiley. Nesta página estão a descrição da obra, os detalhes da edição (456 páginas) e os formatos disponíveis para baixar: pdf, mp3, áudio-livro, kindle. Se você gosta de Livros Internacionais, Administração, Negócios e Economia, Finanças, Finanças e Investimentos, explore também outros títulos da mesma categoria no LivrosQualidade. Veja ainda as outras obras de o autor em nosso catálogo.
Autores populares
Icon Group International (289) Publishing lmgdaw (229) Nikolay Krechet (123) Kennie B Journals (118) Charles Nehme (107) webmarbook design (98) Riddler Books (94) Ondrej Sarek (87) Jillo Trukudo (77) dkdesigns Publishing (76) Mint and Cherry Notebooks (74) Maria Emmrich (73) Just Visualize It (72) Various (69) Moonpeak Library (67) Reynhard Boegl (67) Bettina Schipp (66) matlasor Sticker's (66) Talor Press (66) Joseph Alexander (65)Principais publicadores
Forgotten Books Independently published Routledge Wiley Taschen CRC Press Dover Publications Oxford University Press Springer Princeton University Press Cambridge University Press Kessinger Publishing Bloomsbury Academic Editorial Tirant lo Blanch Hal Leonard Publishing Corporation O'Reilly Media Gale, U.S. Supreme Court Records Thames & Hudson Audible Studios Tuttle Publishing