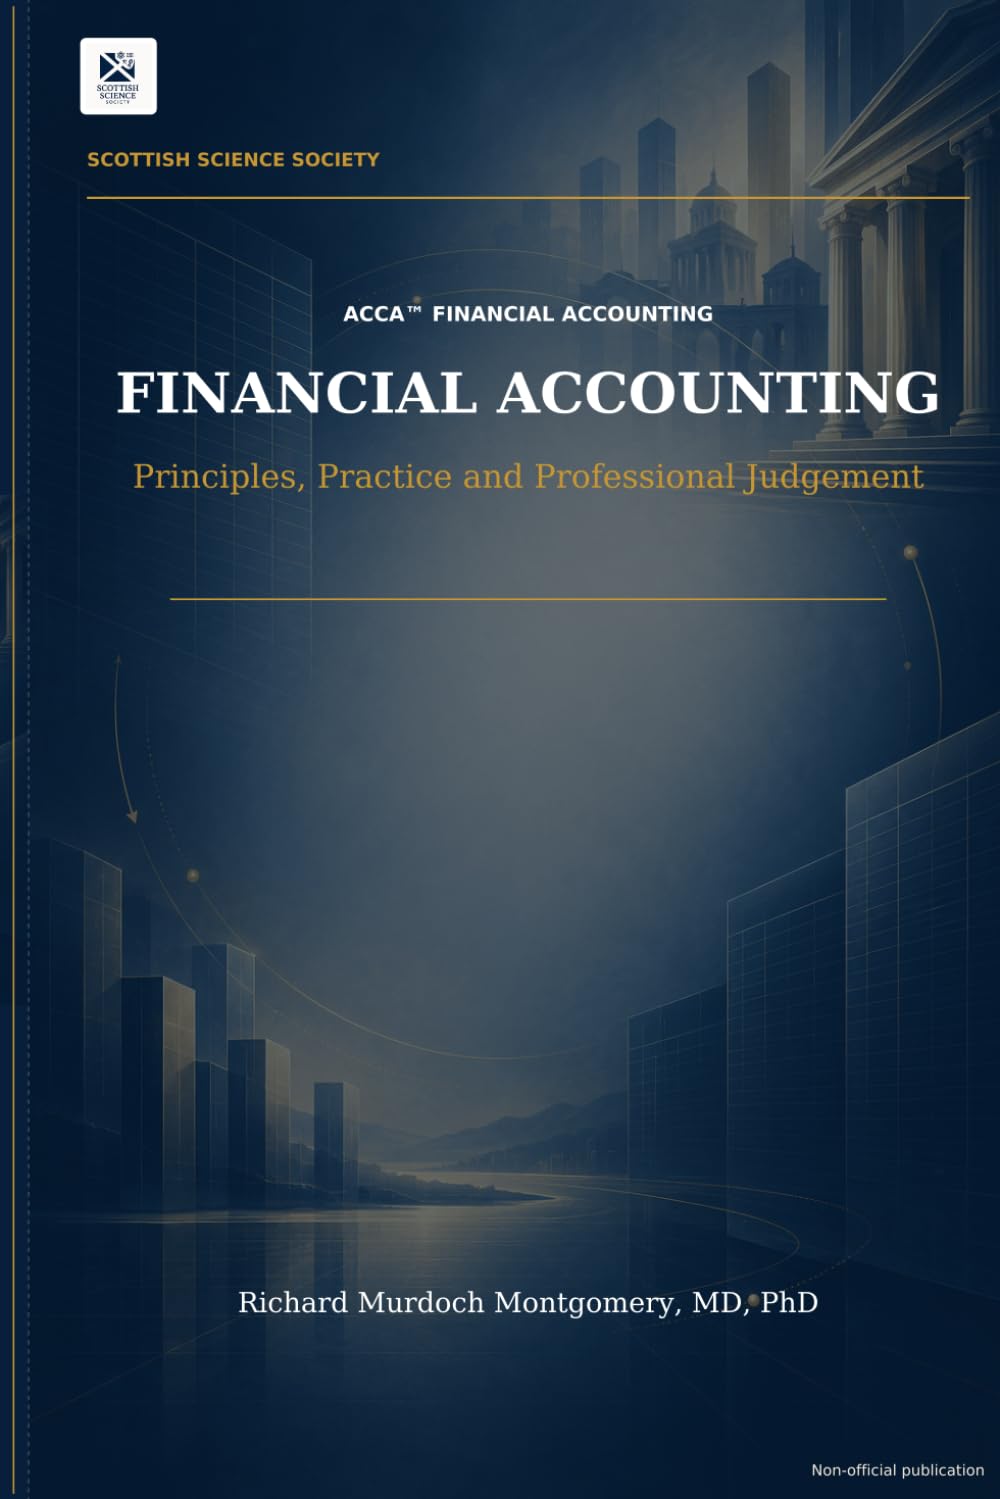
Financial Accounting: Principles, Practice and Professional Judgement baixar o livro de graça
de Richard Murdoch Montgomery
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| Baixar grátis | |
| mp3 | Baixar grátis |
| audiobook | Baixar grátis |
| kindle | Baixar grátis |
Financial Accounting: Principles, Practice and Professional Judgement
Before a transaction can be recorded, it must be understood as an event with
consequences. Before a financial statement can be trusted, its purpose must be
known. This chapter therefore considers accounting as a practice of
representation, communication, judgement, and restraint. It does not yet teach
the mechanics of double entry; a tool deserves an introduction before it is
placed in the hand.
Clerks at work in a nineteenth-century record office. The image is not
offered as a nostalgic argument for ink and paper. Its value lies in the visible
discipline of evidence, classification and custody that survives every change of
technology.
Accounting is the disciplined identification, recording, classification,
measurement, summarisation, interpretation and communication of information
about an entity's economic affairs. The definition is longer than the word's
daily use permits, but it must be. A mere record is not yet accounting; a receipt
in a drawer is evidence, though it has not developed the ambition to become a
financial statement. Nor is a financial statement accounting in its entirety, for it
is the visible conclusion of a process that began with an event, a claim, a
resource, or an obligation.
Accounting then selects, classifies and measures
aspects of that event so that interested persons may reason about it. This
distinction matters, inquirer, because a carefully prepared report may be
imperfect without being dishonest; its unavoidable selectivity is part of its
nature, while its concealment of relevant information would be a different and
more serious matter.
The opposing proposition is that accounting is not merely representational. By
choosing categories, by applying recognition rules and by fixing reporting
periods, it gives commercial life a form in which it may be compared,
questioned and governed. The accounts do not create a debt; nevertheless, the
faithful recording of the debt makes a creditor's claim visible, comparable and
difficult to forget. The synthesis is therefore straightforward: accounting
represents economic reality through conventions that make rational scrutiny
possible. Ideal for ACCA Preparation.
Procurando Financial Accounting: Principles, Practice and Professional Judgement? Aqui você encontra tudo sobre este livro de Richard Murdoch Montgomery. Nesta página estão a descrição da obra, os detalhes da edição (756 páginas) e os formatos disponíveis para baixar: pdf, mp3, áudio-livro, kindle. Se você gosta de Livros Internacionais, Administração, Negócios e Economia, Indústrias e Profissões, Contabilidade, Financeiro, explore também outros títulos da mesma categoria no LivrosQualidade. Veja ainda as outras obras de Richard Murdoch Montgomery em nosso catálogo.
Autores populares
Icon Group International (289) Publishing lmgdaw (229) Nikolay Krechet (123) Kennie B Journals (118) Charles Nehme (107) webmarbook design (97) Riddler Books (94) Ondrej Sarek (87) Jillo Trukudo (77) dkdesigns Publishing (76) Mint and Cherry Notebooks (74) Maria Emmrich (73) Just Visualize It (72) Various (69) Moonpeak Library (67) Reynhard Boegl (67) Bettina Schipp (66) matlasor Sticker's (66) Talor Press (66) Joseph Alexander (65)Principais publicadores
Forgotten Books Independently published Routledge Taschen CRC Press Dover Publications Oxford University Press Springer Princeton University Press Wiley Cambridge University Press Kessinger Publishing Bloomsbury Academic Editorial Tirant lo Blanch Hal Leonard Publishing Corporation O'Reilly Media Gale, U.S. Supreme Court Records Thames & Hudson Audible Studios Tuttle Publishing